
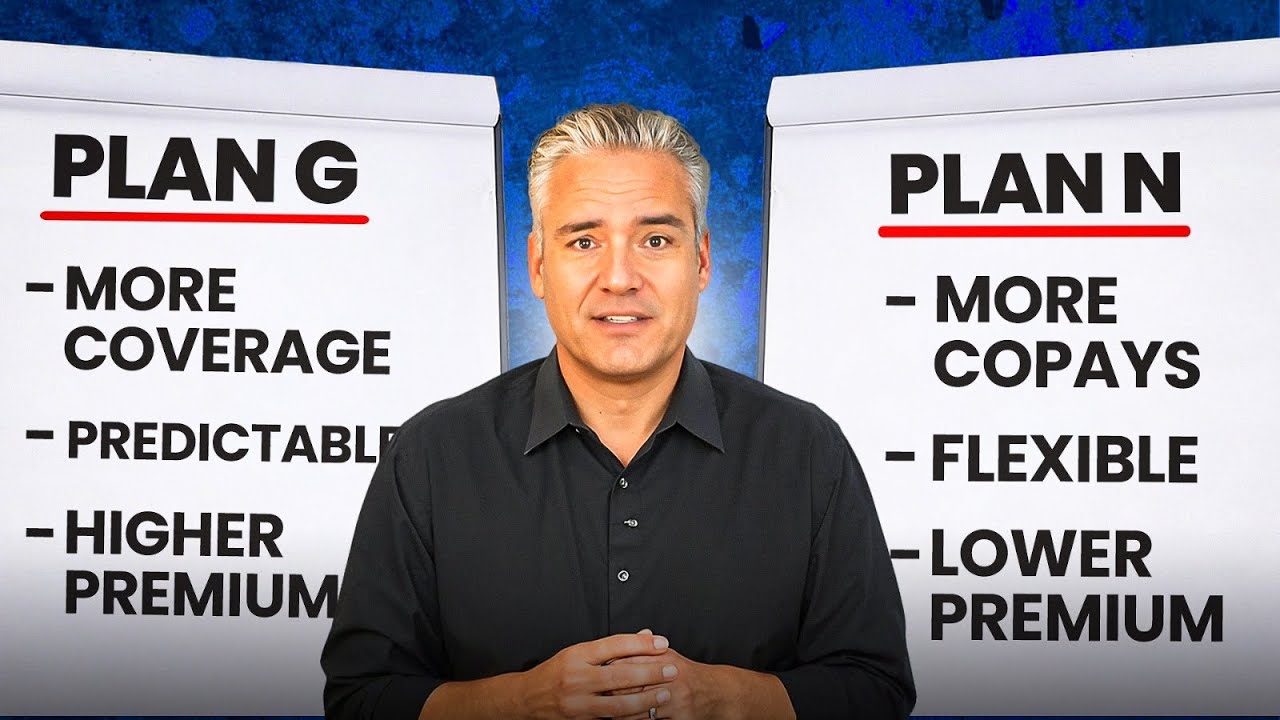
Medicare Supplement Plan G covers more than Plan N. So, Plan G must be the better choice, right?
Not so fast.
Plan N usually has a lower monthly premium than Plan G. But that doesn’t automatically make Plan N the better deal, either.
Here’s the problem. Too many people compare Medicare Supplement plans by looking at which one covers the most or which one has the lowest monthly premium. Neither approach tells you the whole story.
The real question isn’t whether Plan G or Plan N is better. It’s which one is better for you.
I’ve spent more than two decades working inside Medicare insurance companies, and I’ve seen how these decisions play out from both sides. The benefits matter. The premiums matter. But so do the insurance company behind your policy, your healthcare needs, and how comfortable you are with the occasional medical bill.
Let’s compare Plan G vs. Plan N, look at where each plan comes out ahead, and talk about a few things most comparisons leave out.
Plan G vs. Plan N: What’s the Difference?
Plan G and Plan N are both Medicare Supplement insurance plans, also called Medigap. They work alongside Original Medicare Parts A and B to help pay certain out-of-pocket healthcare costs that Medicare doesn’t fully cover.
Both plans offer comprehensive coverage. Both give you broad access to doctors and hospitals that accept Medicare. And both help make your healthcare expenses more predictable than relying on Original Medicare alone.
The main difference comes down to what you’re willing to pay upfront versus what you’re comfortable paying when you actually need care.
Plan G generally has higher monthly premiums but fewer out-of-pocket expenses for Medicare-covered services. Plan N typically has lower premiums but requires some copays and leaves you responsible for potential Part B excess charges.
Here’s how they compare.
| Coverage or Feature | Plan G | Plan N |
|---|---|---|
| Monthly premium | Generally higher | Generally lower |
| Part A hospital coinsurance | Covered | Covered |
| Part A deductible | Covered | Covered |
| Part B coinsurance | Covered | Covered, except certain copays |
| Part B deductible | Not covered | Not covered |
| Doctor office visit copays | None for Medicare-covered services after the Part B deductible | Up to $20 for certain visits |
| Emergency room copays | None for Medicare-covered services after the Part B deductible | Up to $50 if not admitted |
| Part B excess charges | Covered | Not covered |
| Provider networks | No Medigap-specific network | No Medigap-specific network |
| Foreign travel emergency | 80%, subject to plan limits | 80%, subject to plan limits |
| Prescription drug coverage | Not included | Not included |
Now, a comparison chart is helpful. But it doesn’t tell you which plan makes more sense for your life.
For that, we need to go a little deeper.
Doctor Access: It’s a Tie
One of the biggest misconceptions about Plan G and Plan N is that the more comprehensive plan somehow gives you better access to doctors.
It doesn’t.
Both plans work with Original Medicare, which means neither one operates like a Medicare Advantage HMO or PPO with its own provider network.
Generally speaking, if your doctor or hospital accepts Medicare, either supplement can help cover eligible costs according to its standardized benefits.
That’s a big advantage for people who travel frequently, spend part of the year in another state, or see several specialists.
You don’t have to worry about whether a particular cardiologist is in your Plan G network or whether a hospital participates in your Plan N network.
There is no Plan G network. There is no Plan N network.
Matt Tip: Don’t let someone convince you that Plan G offers better doctor access than Plan N. Both plans use the same Original Medicare provider structure. The differences are in cost-sharing, not provider networks.
Monthly Premiums: Plan N Usually Wins
Here’s where Plan N gets interesting.
In most markets, Plan N has a lower monthly premium than Plan G. That difference is one of the biggest reasons people choose it.
But there’s a question I always encourage people to ask:
Is Plan N cheaper enough?
Let’s say you’re comparing two policies, and Plan N saves you $50 per month.
That’s $600 per year in premium savings.
Now imagine Plan N only saves you $10 per month. That’s $120 annually.
Those are two very different financial situations.
In the first example, you could pay several doctor visit copays and still come out ahead with Plan N.
In the second, a handful of copays might eliminate your savings entirely.
The point isn’t that one plan is automatically more affordable. It’s that you have to look at the premium difference alongside your expected healthcare use.
And remember, both plans require you to continue paying your Medicare Part B premium and the annual Part B deductible.
Out-of-Pocket Costs: Plan G Offers More Predictability
This is where Plan G shines.
Once you’ve met your annual Part B deductible, standard Plan G generally covers the remaining Medicare-approved cost-sharing for services covered under its benefits.
For someone who sees multiple specialists, has regular medical appointments, or simply dislikes dealing with medical bills, that predictability can be worth paying more each month.
Think of Plan G as the pay more monthly, think less later option.
Plan N works a little differently.
After meeting your Part B deductible, you may still owe:
- Up to $20 for certain doctor’s office visits.
- Up to $50 for emergency room visits that don’t result in an inpatient hospital admission.
- Any applicable Part B excess charges from providers who don’t accept Medicare assignment.
These aren’t necessarily enormous expenses. But they’re expenses you need to account for.
And let’s be honest. Some people don’t mind a $20 bill showing up after a doctor’s appointment. Other people find it incredibly annoying.
Neither reaction is wrong.
The goal is to choose a plan that fits both your finances and your tolerance for dealing with bills.
Part B Excess Charges: An Important Difference
Here’s one of the most misunderstood parts of the Plan G vs. Plan N comparison.
Plan G covers Medicare Part B excess charges. Plan N does not.
So, what exactly are excess charges?
When a doctor accepts Medicare assignment, they agree to accept the Medicare-approved amount as payment in full for covered services.
However, some healthcare providers accept Medicare patients without accepting assignment. In certain situations, those providers can charge more than the Medicare-approved amount, generally subject to a federal limiting charge.
That additional amount is called a Part B excess charge.
Plan G covers eligible Part B excess charges. Plan N leaves you responsible for them.
Sounds like a major reason to avoid Plan N, doesn’t it?
Not necessarily.
Most Medicare claims are accepted on assignment, so excess charges are much less common than some insurance sales pitches might lead you to believe.
That doesn’t mean they’re impossible. Certain specialties or individual providers may warrant a closer look.
But I wouldn’t automatically eliminate Plan N based on excess charges alone.
Instead, ask your doctors one important question:
“Do you accept Medicare assignment?”
Notice I didn’t say, “Do you take Medicare?”
Those are not exactly the same question.
If you’re considering Plan N, understanding how your doctors bill Medicare can help you avoid an unpleasant surprise.
Long-Term Premium Increases: The Risk People Forget
Now we’re getting into something most Medicare Supplement comparisons barely discuss.
And this is where my experience working inside insurance companies becomes particularly relevant.
Plan G is one of the most comprehensive Medicare Supplement plans available to people newly eligible for Medicare.
Before 2020, Plan F was often the go-to option for people who wanted the richest standardized Medigap coverage. But people who became newly eligible for Medicare on or after January 1, 2020, generally cannot buy Plan F.
That helped make Plan G the new favorite for people seeking more comprehensive coverage.
But there’s another side to that story.
People who expect significant healthcare expenses may naturally gravitate toward plans offering the most predictable cost-sharing.
That can influence the overall claims experience of an insurance company’s Plan G policyholders.
Insurance companies look at claims costs, medical inflation, utilization, administrative expenses, and other factors when determining premiums and requesting rate increases.
And when claims costs rise, premiums may follow.
Here’s the important distinction:
Standardized benefits do not mean standardized premiums or standardized future rate increases.
Two insurance companies can sell the same Plan G benefits and charge very different premiums. Their renewal increases may also differ considerably.
Plan N may have a different mix of policyholders because it tends to attract people who prefer lower monthly premiums and are comfortable accepting some additional out-of-pocket expenses.
That difference can influence long-term pricing in some situations.
However, I want to be careful here. Plan N is not immune to premium increases, and there’s no guarantee that its rates will rise more slowly than Plan G’s.
A well-managed Plan G from a financially strong insurance company may be a better long-term choice than a poorly priced Plan N from another carrier.
Which brings us to an important point.
The insurance company matters just as much as the letter on your Medicare Supplement card.
Why Your Medicare Supplement Insurance Company Matters
Most people compare Plan G and Plan N as if choosing the plan letter finishes the job.
It doesn’t.
Medigap benefits are standardized in most states, meaning Plan G from one insurance company provides the same standardized medical benefits as Plan G from another.
But that doesn’t mean the companies themselves are identical.
Consider what can vary between carriers:
- Monthly premiums and available household discounts.
- Historical premium increases.
- Pricing methods and how premiums change as you age.
- Financial strength and overall business stability.
- Customer service and administrative experience.
- Medical underwriting requirements if you apply for a different policy later.
I’ve seen what happens when insurance companies price aggressively to attract new customers.
A low introductory premium looks great. Agents sell it. Consumers buy it.
Then claims come in higher than expected, the actuarial assumptions don’t hold up, and the company has to adjust its pricing.
Suddenly, that attractive premium doesn’t look quite so attractive anymore.
And unlike switching your streaming service, switching Medicare Supplement insurance companies later may not be simple.
Outside your Medigap Open Enrollment Period or other guaranteed-issue protections, you may have to answer medical underwriting questions. Depending on your health and state rules, an insurance company could charge you more or decline your application.
So, “I’ll just switch later if the premium goes up” isn’t necessarily a strategy.
It’s a hope.
And hope isn’t my favorite Medicare planning tool.
Matt Tip: Ask about a company’s premium history before choosing a policy. The cheapest plan today isn’t necessarily the best value five years from now.
Who Is Medicare Supplement Plan G Best For?
Plan G may be the better choice if you prioritize predictability and want to minimize out-of-pocket bills when you use Medicare-covered healthcare services.
It may be especially appealing if you:
- Visit doctors or specialists frequently.
- Have ongoing healthcare needs or expect major medical treatment.
- Want protection against Part B excess charges.
- Prefer not to pay office visit and emergency room copays after meeting your deductible.
- Can comfortably afford the higher monthly premium.
- Value simpler medical billing over maximizing potential premium savings.
For someone managing multiple chronic conditions or receiving frequent treatments, Plan G’s additional cost-sharing protection can be valuable.
But even if you’re relatively healthy, you may simply prefer its predictability.
Peace of mind has value, too.
Who Is Medicare Supplement Plan N Best For?
Plan N may be an excellent option for people who want comprehensive coverage but prefer a lower fixed monthly premium.
It may fit you well if you:
- Want to reduce your monthly Medicare Supplement costs.
- Don’t visit doctors frequently.
- Are comfortable paying occasional office visit or emergency room copays.
- Have checked whether your providers accept Medicare assignment.
- Understand the possibility of Part B excess charges.
- Have found meaningful premium savings compared with Plan G.
- Are comfortable keeping a little more money in your pocket each month while accepting some additional cost-sharing risk.
Plan N isn’t bare-bones coverage.
It’s a comprehensive Medicare Supplement option that asks you to take on a little more responsibility for certain expenses.
And for the right person, that can be a smart financial trade-off.
How to Decide Between Plan G and Plan N
Let’s make this practical.
Rather than choosing whichever plan sounds better, work through a few simple questions.
1. How much would Plan N actually save you?
Subtract the monthly Plan N premium from the Plan G premium, then multiply that difference by 12.
For example:
- Plan G: $180 per month.
- Plan N: $140 per month.
- Monthly savings: $40.
- Annual savings: $480.
Those are hypothetical premiums, not actual quotes. Your pricing will depend on where you live, your eligibility, and the insurance companies available to you.
2. How often do you expect to visit the doctor?
If you have four office visits with $20 copays under Plan N, that’s $80 in additional expenses.
Against $480 in annual premium savings, Plan N could still leave you ahead.
But if the premium savings are only $120 per year, the calculation becomes much tighter.
Keep in mind that actual copays depend on the services you receive, and excess charges could change the comparison.
3. Do your doctors accept Medicare assignment?
If you’re considering Plan N, check with your current doctors and specialists.
Don’t assume that accepting Medicare always means accepting Medicare assignment.
4. How important is predictable billing?
Some people would rather pay a higher premium and have fewer bills arrive throughout the year.
Others prefer a lower monthly expense, even if that means paying occasional copays.
The right answer depends on your preferences.
5. What do you know about the insurance company?
Compare more than the first-year premium.
Ask about historical rate increases, household discounts, financial stability, and the company’s experience in your state.
Also, find out what your options would be if you wanted to change policies later.
6. Will this decision still make sense in five or ten years?
This may be the most important question.
Your health at 65 may look very different from your health at 75. It helps to understand what changes about Medicare after age 70 before making a long-term decision.
Don’t make a long-term insurance decision based entirely on your healthiest year.
And don’t assume that choosing the richest coverage automatically protects you from rising premiums.
Five Mistakes to Avoid When Comparing Plan G and Plan N
Mistake #1: Assuming Plan G is automatically better because it covers more.
More coverage doesn’t always mean better value. The additional premium needs to make sense for your circumstances.
Mistake #2: Choosing Plan N solely because the premium is lower.
A lower premium is attractive, but understand the copays and potential excess charges before making your decision.
Mistake #3: Ignoring future premium increases.
Your first-year premium is only the beginning. Research the insurance company’s pricing history and consider how future increases could affect your retirement budget.
Mistake #4: Assuming you can easily switch plans later.
Depending on your state and circumstances, changing Medicare Supplement policies may require medical underwriting. Your initial enrollment decision can have long-term consequences.
Mistake #5: Forgetting about Medicare Part D.
Neither Plan G nor Plan N includes outpatient prescription drug coverage. You may need a separate Medicare Part D plan to cover your medications and avoid a potential late enrollment penalty if you don’t have other creditable drug coverage.
A great Medicare Supplement choice paired with the wrong prescription drug plan can still leave you spending more than necessary.
That’s Medicare for you. Fix one thing, and three more decisions are waiting around the corner.
Get Help Comparing Medicare Supplement Plans
Plan G and Plan N aren’t particularly difficult to understand once you break down the differences.
The harder part is comparing actual insurance companies, premiums, rate histories, household discounts, and state-specific enrollment rules.
That’s where a knowledgeable independent Medicare insurance agent can be especially helpful.
An independent agent can compare multiple insurance companies, explain the trade-offs, and help you understand how each option fits your doctors, budget, and healthcare needs.
If you already work with a great independent agent, fantastic. Ask them to compare both Plan G and Plan N rather than assuming one is automatically best.
If you need help, my wife, Niki, runs Brickhouse Agency, an independent Medicare insurance agency that helps people compare Medicare Supplement, Medicare Advantage, and Part D options.
Her team takes an education-first, no-pressure approach. They can help you evaluate the options available where you live and understand how those choices may affect your costs over time.
If you are comparing supplements because your current coverage is changing, start with what to know when Medicare Advantage plans change or end. Then review special enrollment periods after a plan termination so you can discuss your timing and coverage options with an agent.
There’s no obligation to enroll.
And yes, these are the kinds of things Niki and I talk about at home. Some couples discuss dinner plans. We discuss Medicare Supplement loss ratios and Part B excess charges.
Romantic? Questionable. Useful? Absolutely.
The Bottom Line: Plan G vs. Plan N
Both Plan G and Plan N are strong Medicare Supplement choices. Neither one is universally better.
Plan G generally offers greater predictability, fewer out-of-pocket bills for Medicare-covered services, and protection against Part B excess charges.
Plan N typically offers lower monthly premiums in exchange for occasional copays, potential excess charges, and a little more attention to how your providers bill Medicare.
But don’t forget the insurance company behind the policy.
The richest plan isn’t automatically the best long-term value. And the cheapest premium today isn’t necessarily the smartest long-term decision.
The better question is this:
Which plan fits my health, my doctors, my budget, and my comfort with future costs?
That’s how you make a Medicare decision you can feel confident about.
And that’s what preparing for Medicare is really all about.
I’m Matt Feret. Here’s to your wealth, wisdom, and wellness.
Frequently Asked Questions About Plan G vs. Plan N
Is Medicare Supplement Plan G better than Plan N?
Not necessarily. Plan G covers more out-of-pocket costs for Medicare-approved services, including Part B excess charges, and generally eliminates the copays associated with Plan N. However, Plan N typically has lower monthly premiums. The better choice depends on your healthcare needs, budget, and preferences.
What is the biggest difference between Plan G and Plan N?
The biggest differences are monthly premiums, copays, and Part B excess charge coverage. Plan G generally costs more each month but provides more predictable medical cost-sharing. Plan N usually costs less but may require certain office visit and emergency room copays and does not cover Part B excess charges.
Does Plan N have a deductible?
Yes. Like standard Plan G, Plan N does not cover the annual Medicare Part B deductible. You’ll need to meet that deductible before the plans pay applicable Part B cost-sharing benefits. Both plans cover the Medicare Part A deductible.
Does Plan N cover hospital stays?
Yes. Plan N covers the Medicare Part A deductible, Part A hospital coinsurance, and eligible hospital costs for up to an additional 365 days after Medicare benefits are used, according to standardized Medigap benefits.
Does Plan N cover Part B excess charges?
No. Plan N does not cover Medicare Part B excess charges. If a provider who doesn’t accept Medicare assignment bills an allowable excess amount for a Medicare-covered Part B service, you may be responsible for that charge. Standard Plan G covers eligible Part B excess charges.
Do Plan G and Plan N cover prescription drugs?
No. Neither plan includes outpatient prescription drug coverage. You can generally purchase a separate Medicare Part D plan to help cover prescription medications.
Can I switch from Plan N to Plan G later?
Possibly, but switching isn’t always guaranteed. Outside your Medigap Open Enrollment Period or certain guaranteed-issue situations, insurance companies may use medical underwriting when evaluating your application. Some states provide additional switching protections, so check the rules where you live.
Schedule Your FREE Medicare Consultation
Whether you’re new to Medicare, turning 65, retiring, or looking to change plans, the licensed agents at Brickhouse Agency offer free, no-obligation consultations to walk you through your options.
Required Medicare Disclaimer: No obligation to enroll. Brickhouse Agency does not offer every plan available in your area. For information on all your options, visit Medicare.gov or call 1-800-MEDICARE.